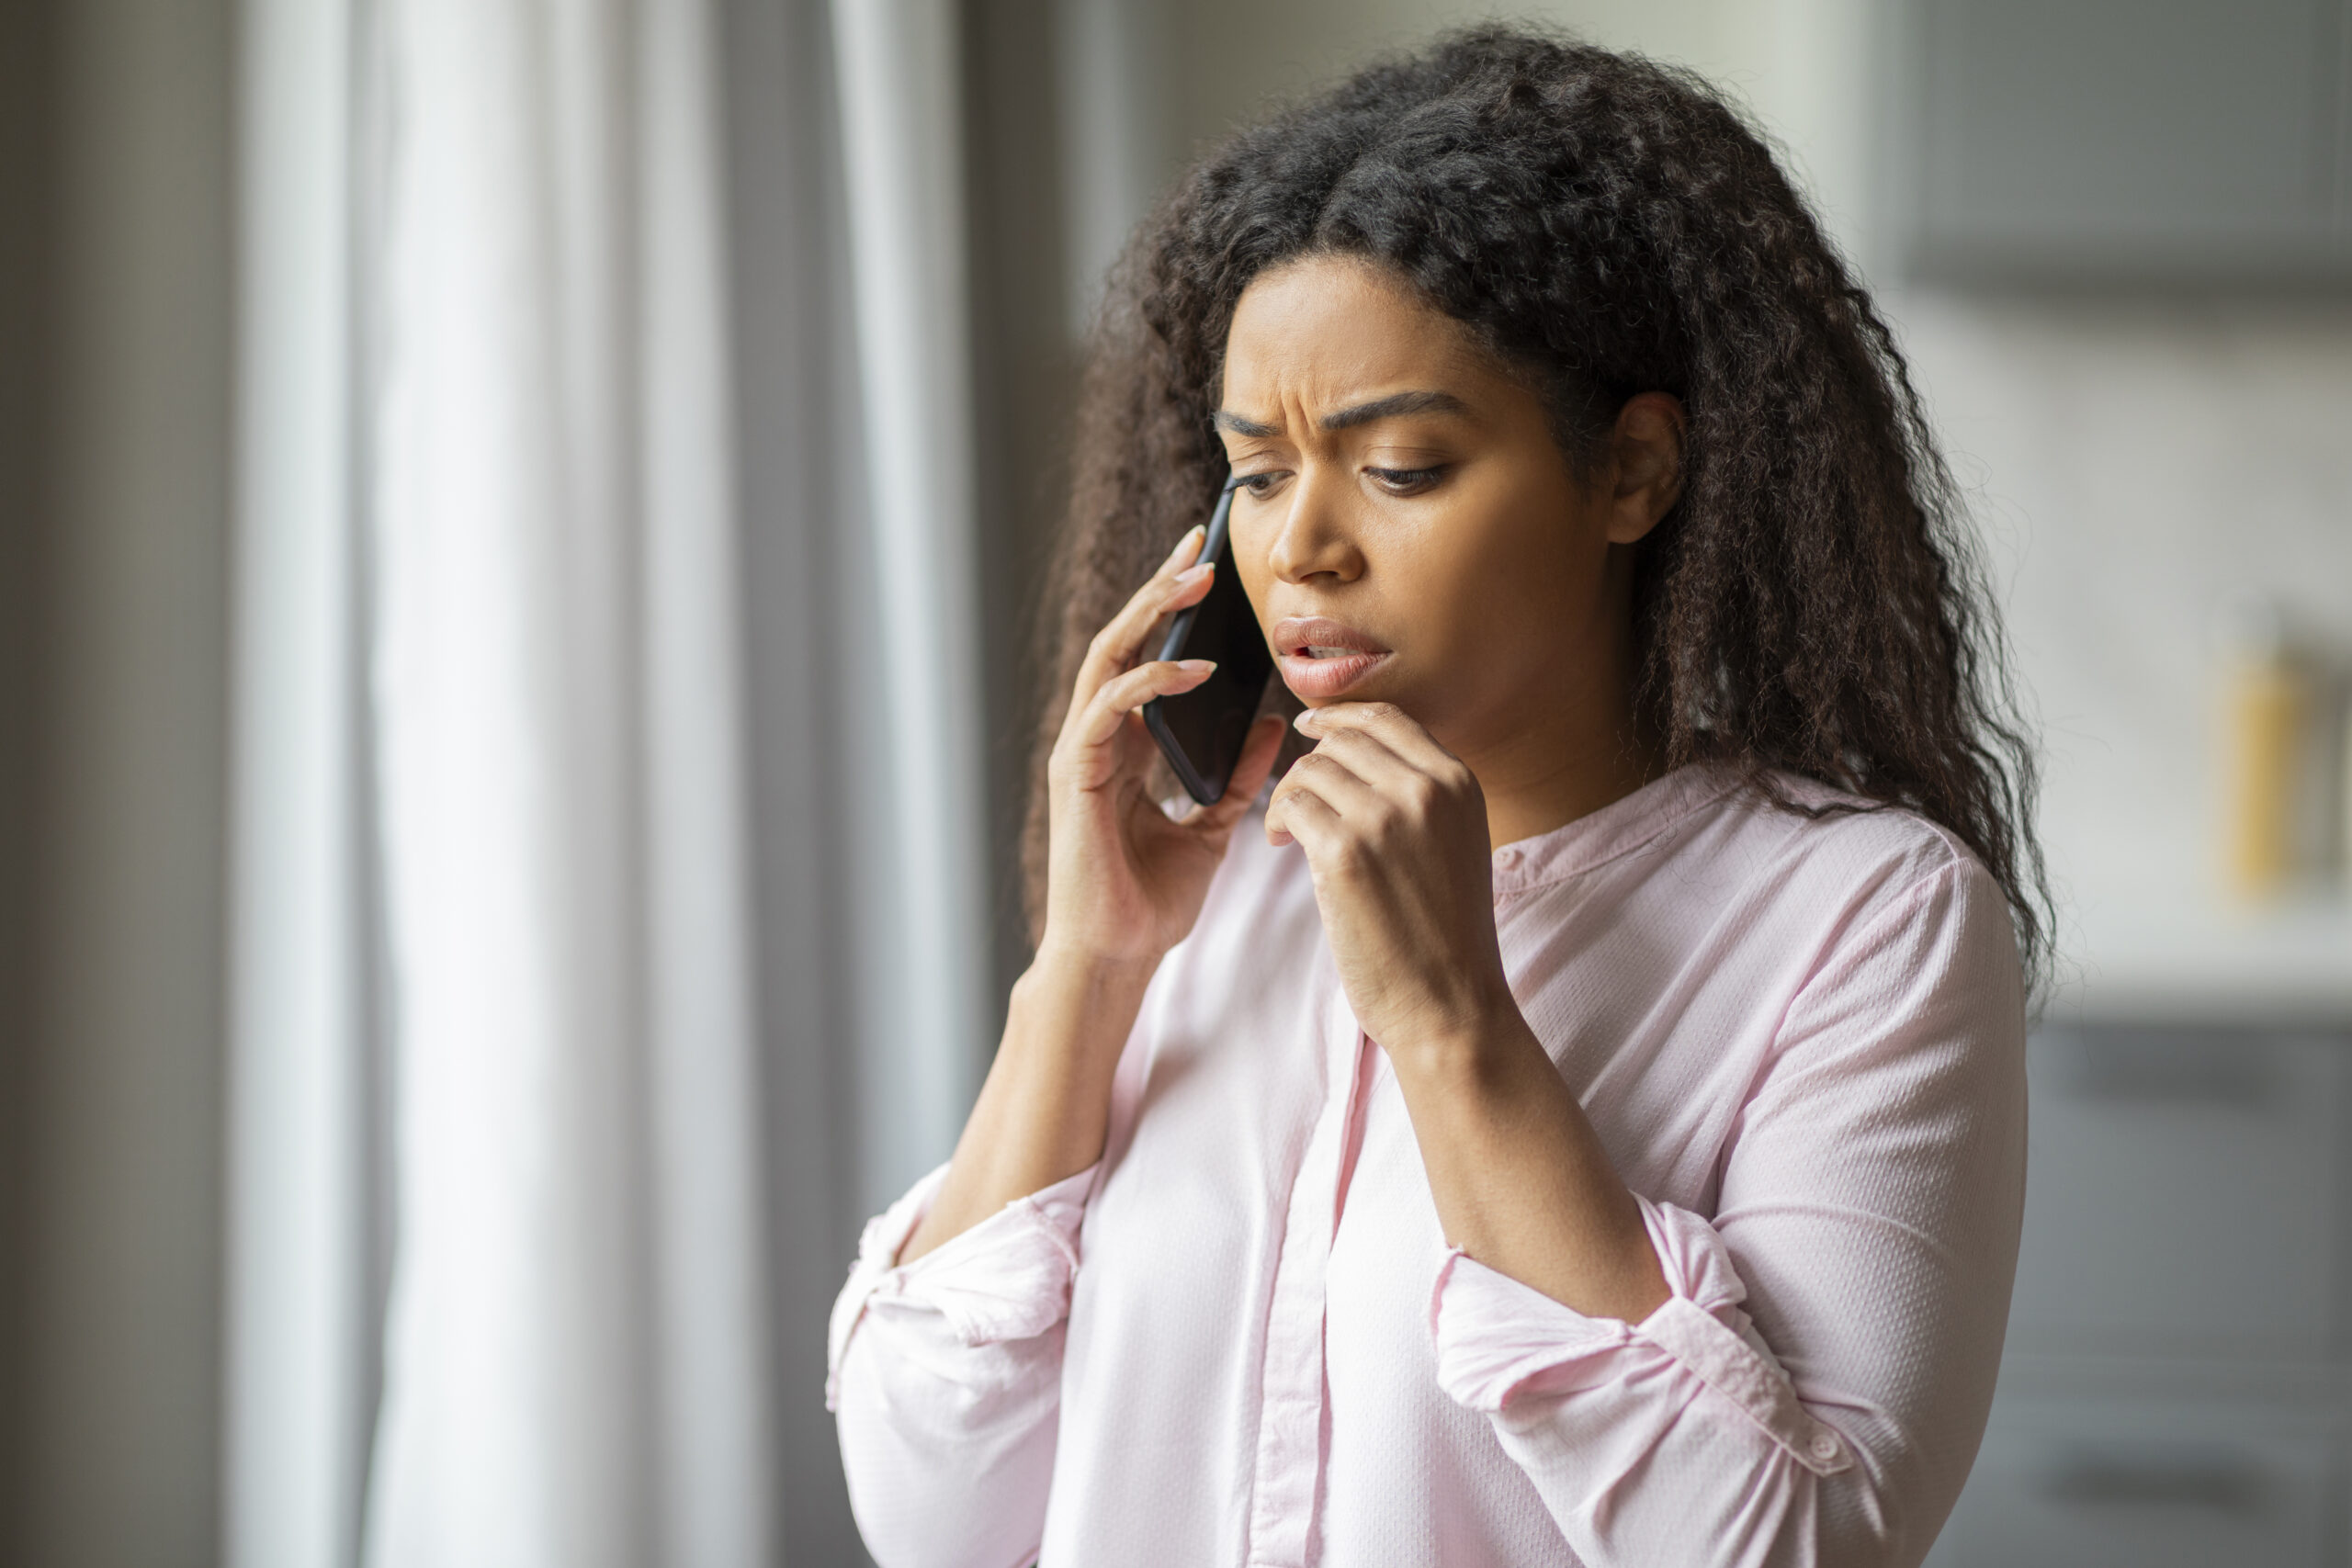
The call often comes within a day or two of an accident. A friendly insurance adjuster explains that they just need to “get your side of the story” and asks if they can record the conversation. It can feel like a routine step, and saying no can feel uncooperative. But a recorded statement can have lasting consequences for your injury claim, and in many cases, you are not required to give one.
What Is a Recorded Statement?
A recorded statement is an interview, usually by phone, in which an insurance adjuster asks you questions about the accident and your injuries while recording your answers. The adjuster typically asks how the accident happened, what you saw, how fast vehicles were traveling, what injuries you have, and what medical treatment you have received. The recording becomes part of the insurance company’s file and can be used later in the claim or in a lawsuit.
The Other Side’s Insurance Company
If the request comes from the at-fault driver’s insurance company, or from the insurer for a property owner after a fall, you generally have no legal obligation to give a recorded statement. You do not have a contract with that company, and its adjuster’s job is to protect its own policyholder and limit what the company pays.
You can politely decline. A simple response such as “I’m not comfortable giving a recorded statement at this time” is enough. Declining a recorded statement to the other side’s insurer generally does not prevent you from pursuing a claim.
Your Own Insurance Company
Your own insurance company is different. Most auto policies include a cooperation clause, which generally requires you to report an accident promptly and assist with the company’s investigation. If you are seeking benefits under your own policy, such as medical benefits or uninsured or underinsured motorist coverage, your insurer may ask for a statement, and refusing to cooperate can put your coverage at risk.
Even so, cooperating does not mean you must answer questions on the spot. You can generally ask to schedule the statement for a later time, ask what topics will be covered, and speak with a lawyer first. When you are making an uninsured or underinsured motorist claim, keep in mind that your own insurer’s financial interests are opposed to yours, even though you are its customer.
How a Recorded Statement Can Hurt Your Claim
Most people giving a recorded statement are trying to be honest and helpful. The problem is that statements given soon after an accident are often incomplete, and insurance companies are trained to use them to reduce what they pay. Common problems include:
- Downplaying your injuries. Saying “I’m fine” or “just a little sore” before you have seen a doctor can be used later to argue that your injuries are minor or were caused by something else.
- Guessing about details. Estimates of speed, distance, or timing are often wrong, and an incorrect guess can later be used to question your credibility.
- Accepting partial blame. Casual comments like “I didn’t see them” or “I might have been going a little fast” can be used to argue that you share the fault for the accident.
- Inconsistencies. Small differences between a recorded statement and later testimony can be used to suggest that your account is unreliable.
If You Do Give a Statement
If you decide to give a recorded statement, or your policy requires one, a few practices can help protect you:
- Stick to facts you know. It is fine to say “I don’t know” or “I’m not sure” rather than guessing.
- Do not speculate about fault. Describe what happened, and let the evidence speak for itself.
- Be accurate about your injuries. If you are still being evaluated or treated, say so, rather than describing your condition as minor.
- Keep it short. Answer the question asked, without volunteering extra information.
Other Requests to Watch For
Recorded statements are not the only early requests insurance companies make. Adjusters may also ask you to sign a broad medical authorization that gives them access to your entire medical history, or offer a quick settlement before the full extent of your injuries is known. Signing a release as part of a settlement generally ends your claim for good, even if your injuries later turn out to be more serious than you realized. It is wise to have a lawyer review any document an insurance company asks you to sign.
How Wood Legal Can Help
When you have a lawyer, insurance companies generally communicate through your lawyer rather than contacting you directly, which helps protect you from statements that could later be used against you. Pennsylvania also has strict time limits for filing personal injury claims, so it is important to get advice early. Wood Legal represents injured people only, never insurance companies, and personal injury cases are handled on a contingency basis, with no upfront cost. Contact us today for a free case review.